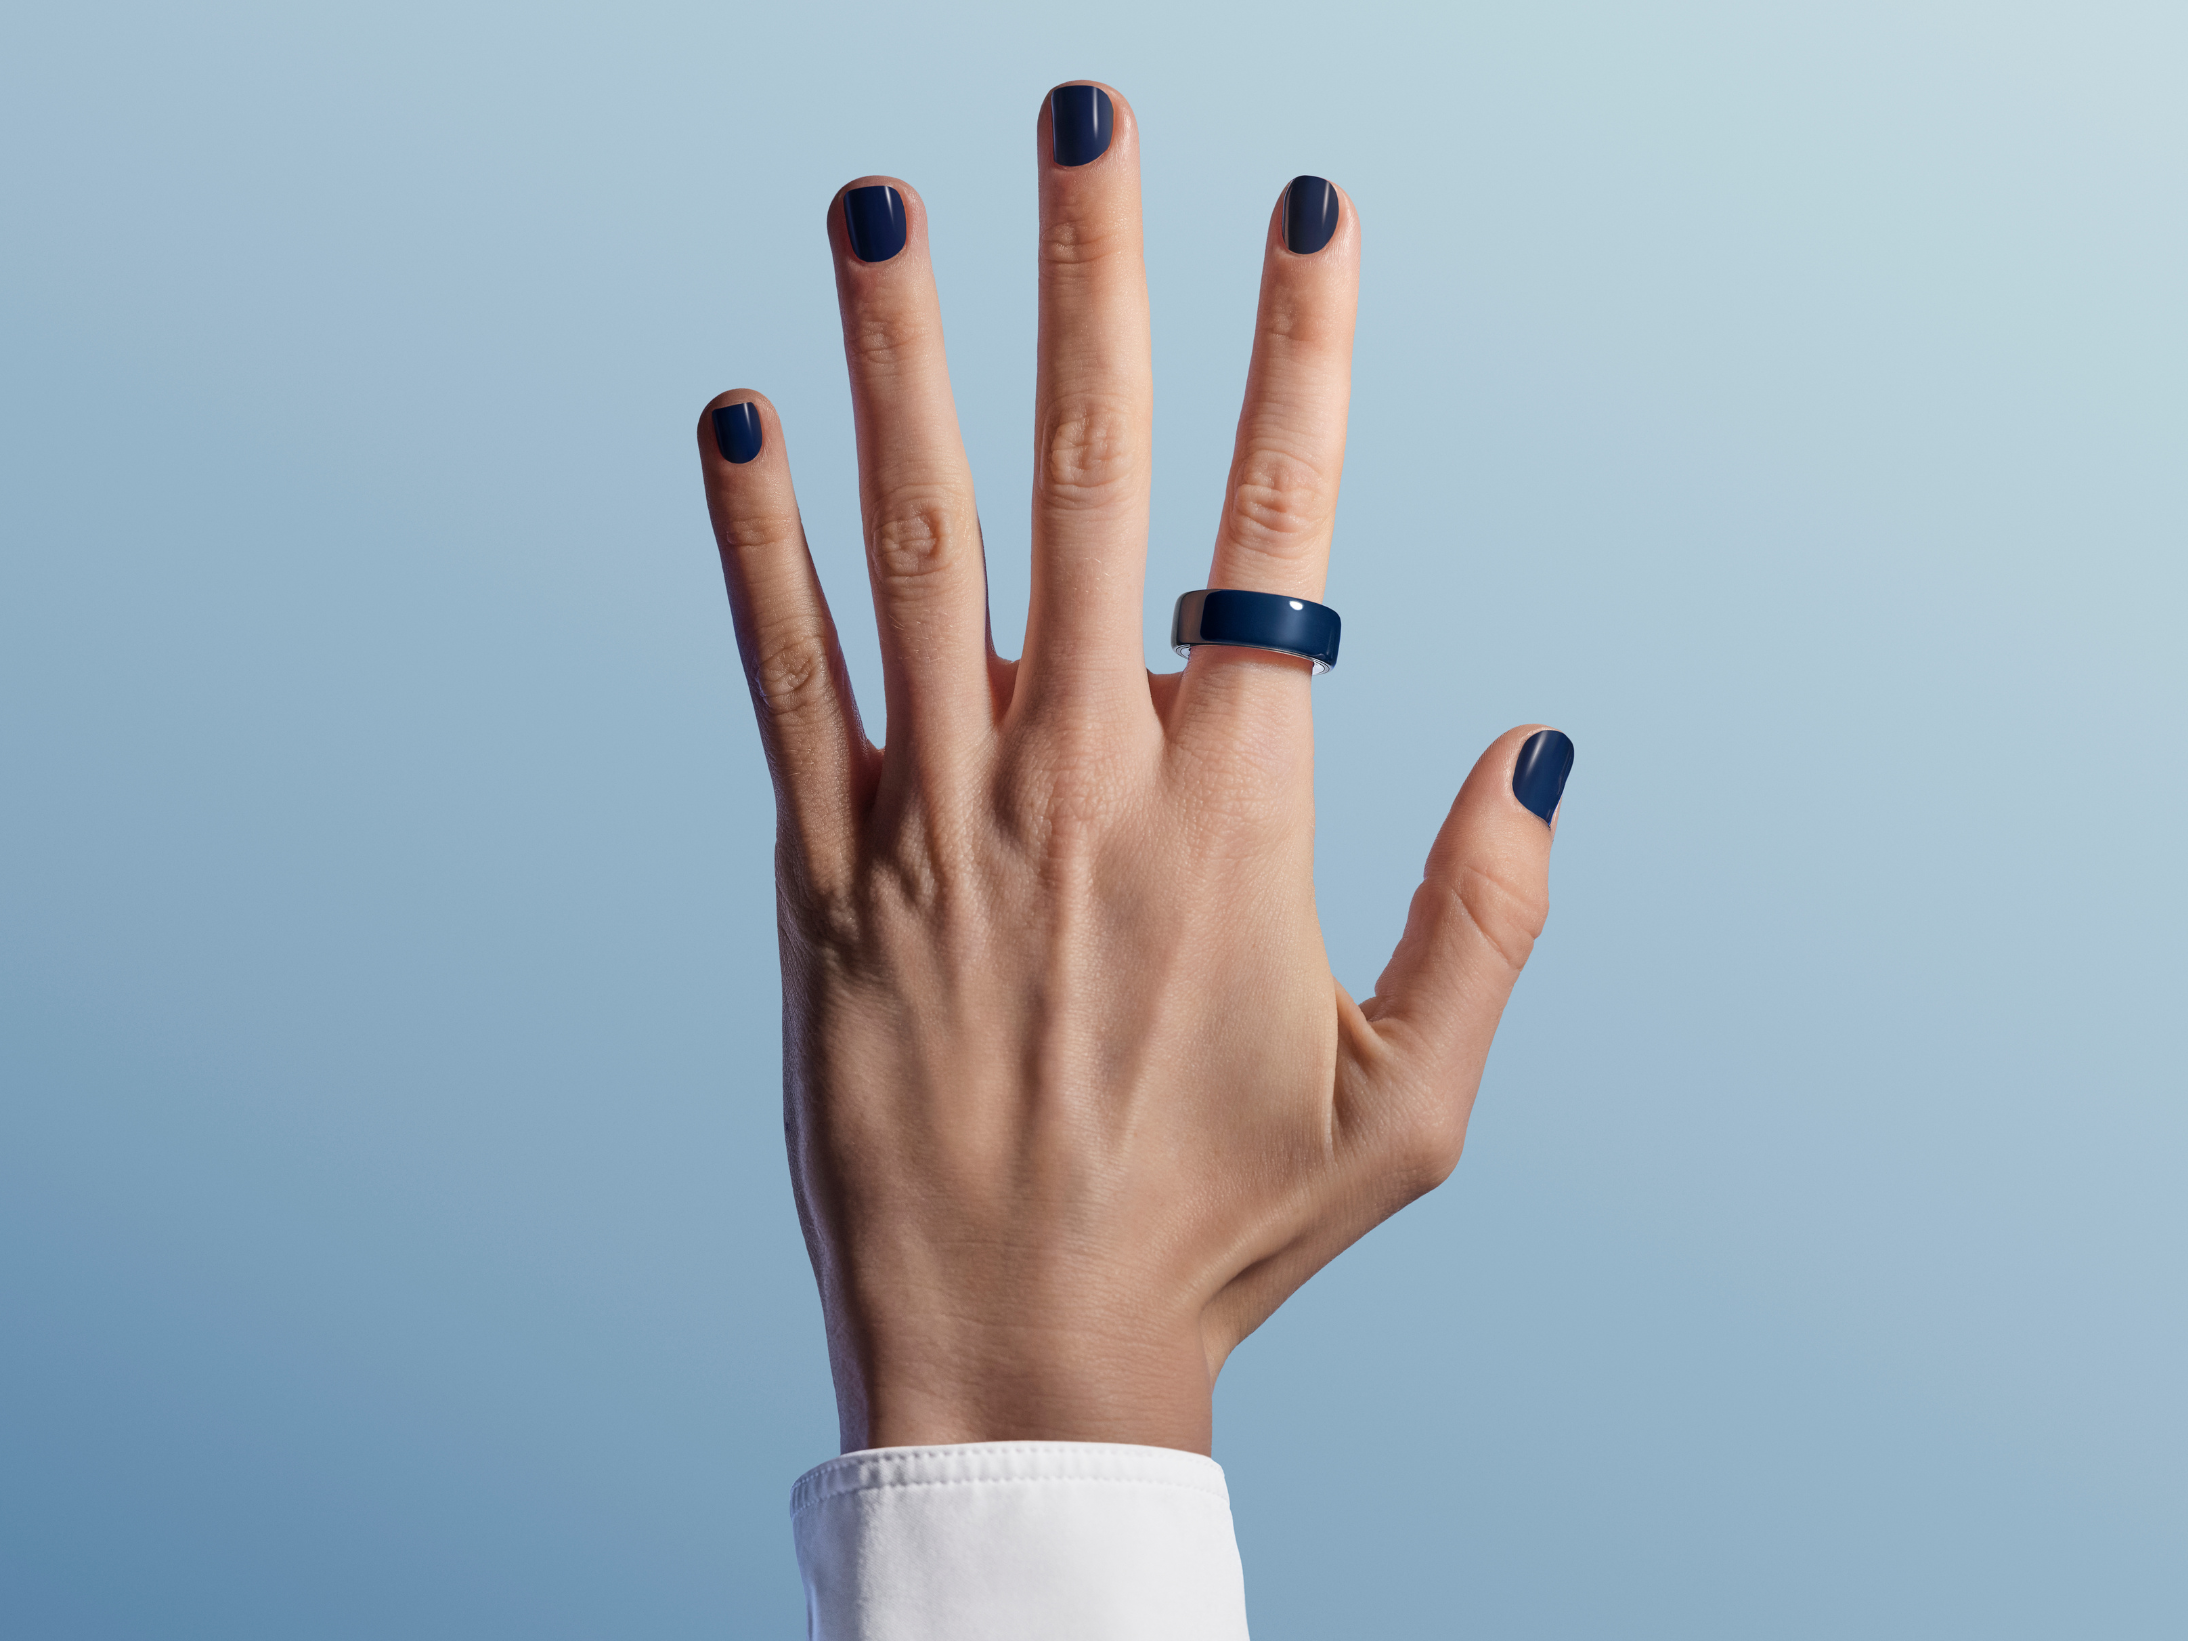
Oura Inc. filed its Form S-1 with the SEC on 3 September 2026. This document is a treasure trove of financial data, market insights, and other consumer-health related intel!
The company is reported to plan to raise up to $3bn at a valuation above $16bn (£11.8bn). This note highlights the key figures in the filing and readacross for our Consumer Health thesis.
Insights from the Oura IPO filing Trailing revenue is $1,425m (£1,052m), up 74% year on year for the nine months to June 2026, with trailing net income of $59m (£44m). They also now have 5m paid members - we’ll get onto retention later in the doc!
Oura’s operating margin is 4.0% on a trailing basis, against 3.3% in FY24 and 5.0% in FY25. Revenue has grown 3.5x since FY24 while maintaining operating margin in the mid-to-low single digits.
Hardware revenue was 80% of revenue in the nine months to June 2026 and 83% in FY25. Membership has moved from 19% of revenue in FY24 to 20% on a trailing basis, five years after launch (membership launch, that is!). Again we will talk about retention later on but should expect membership revenue to start stacking in the steady state.
Gross margin was 64.9% in FY24, 51.9% in FY25 and 54.5% trailing. The MD&A attributes the fall from page 88 onwards; the risk factors name Ring 4 warranty replacements and tariffs on imports from six countries as contributors (I definitely experienced this and this has caused me to cancel my Oura subscription as of 1 month ago!).
Selling and administrative cost is 33.2% of revenue, close to Birkenstock’s 32.9% and Peloton’s 34.0% . Garmin runs 17.4% and Apple 6.6% . Oura also carries R&D at 17.4% of revenue; Birkenstock whereas reports no R&D line (these are different reporting requirements between US and EU/UK disclosures).
72% of members are women, with female membership compounding at 143% a year since FY24 against 94% for men. 31% of members are 29 or under and 27% are 46 or over. 37% report household income below $100,000.
33% of new members report Oura as their first wearable, 29% replaced an existing one and 37% wear another alongside it. I though this piece was interesting, as it still implies almost 2/3 people have already tried a wearable ahead of Oura.
Twelve-month paid member retention is 85% , measured inclusive of winbacks . Nothing is disclosed about retention beyond month 12. DAU-to-MAU is 65% which is actually lower than I’d expected given the daily use nature of the interface.
At the reported $16bn target, the multiples are 11.2x trailing revenue and 163x trailing adjusted EBITDA. The October 2025 Series E priced the company at about $11bn on roughly $1bn of calendar-2025 revenue, or about 11x.
The filing’s largest study has more than 350,000 participants . The reported health improvements of 90%, 88%, 81% and 73% come from a 479-person survey conducted in July 2024.
We’ll watch how the markets view Oura in the coming weeks, with the listing rumoured to happen by the end of the month. As always, get in touch with thoughts or feedback!
Thanks for reading Eka Ventures Newsletter! Subscribe for free to receive new posts and support my work.

11.9.26
Key figures from Oura’s IPO filing
Issue 167 l Eka’s Weekly Roundup (11 September 2026)